
Major life shifts—such as welcoming a new child, changing employment, or relocating between cities like Burlington and Montpelier—require immediate policy adjustments. A new baby necessitates evaluating life insurance to secure long-term education and childcare funding, while a new home often demands updated dwelling limits that reflect current construction costs and property values. Even minor home improvements, such as a new roof or a finished basement, can leave a policyholder underinsured if the coverage isn't updated to account for increased asset value.
Why Vermont Families Should Audit Insurance Policies Annually
Life in Vermont rarely stays static, yet many households rely on outdated insurance policies that no longer match their current reality. Newport-based insurance expert Heather Trudeau argues that an annual review of home, auto, and life coverage is the only way to ensure financial protection keeps pace with evolving personal circumstances.
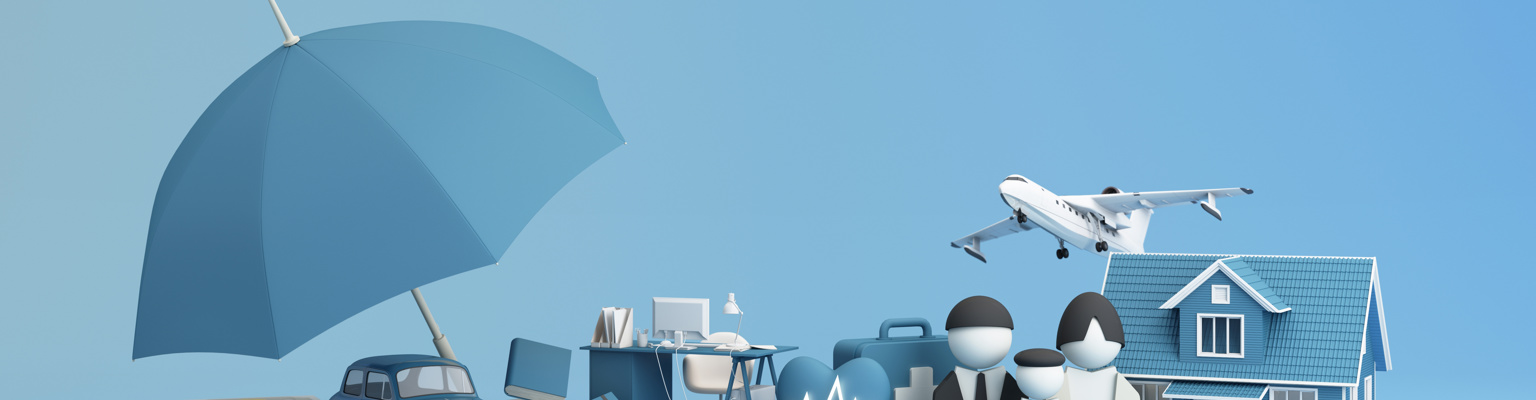
Beyond personal milestones, economic factors like inflation and seasonal risks demand attention. Rising repair costs mean that older policies may fail to cover the true price of restoring a property after a harsh Vermont winter or a storm. Furthermore, driving habits change; annual reviews allow families to adjust liability limits and deductibles to match current budgets and vehicle usage. Beyond maintaining safety, these periodic check-ins often uncover eligibility for new discounts, helping families optimize their premiums while eliminating coverage for assets or risks that no longer exist.
Comments (0)
No comments yet. Be the first!